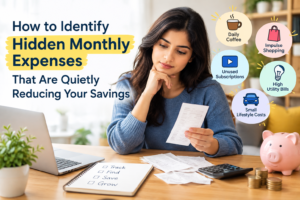



Most people who struggle to save aren’t overspending on big things. The leak is usually a dozen small charges that nobody decided on recently. Rent, groceries, and EMIs get attention because they’re large and visible. The expenses that hurt savings are small, automatic, and easy to forget.
Everything below is based on how recurring billing and budgeting actually work. The numbers are illustrations you can replace with your own, not statistics from a study.
Quick links on this site: EMI Calculator · Blog · About · Contact
1. Why hidden expenses drain savings so effectively
They’re small enough to ignore. A $5 to $15 charge never triggers a “should I buy this?” moment, yet twelve of them add up to a real bill.
They’re automatic. You decided once, months or years ago, and the money has left your account every month since. Nothing prompts you to decide again.
They hide inside bigger numbers. A statement with 60 transactions doesn’t reveal that three of them are the same kind of recurring charge. Different billing names for the same company make this worse.
They grow quietly. Introductory prices end, plans auto-upgrade, and insurance premiums rise at renewal. What you pay now may differ from what you agreed to.
Their real cost is what the money could have become. A $120 monthly leak is $1,440 a year. Invested monthly at a modest 6% annual return, that $120 grows to roughly $19,700 in ten years. In rupee terms, ₹5,000 a month at the same rate becomes about ₹8.2 lakh. You can test your own figures with the compounding tools on the site; the homepage lists a Compound Interest Calculator and an Investment Return Calculator, which you can link here once their pages are live.
Mental accounting makes it worse. People tend to treat small recurring charges as “background noise” rather than part of their budget, so they never get compared against goals like an emergency fund or a down payment.
2. The main categories of hidden expenses
A. Subscriptions and memberships
- Streaming, music, cloud storage, news, and premium app tiers
- Gym or club memberships you rarely use
- Subscriptions billed through your phone’s app store, which show up under Apple, Google, or a wallet name rather than the service itself
- Free trials that converted to paid plans, often at full price
- Family or shared plans where the other members stopped using the service
- Annual plans that renew automatically, sometimes with a price rise and only a brief email notice
Where to look in India: UPI AutoPay mandates (in your UPI app’s mandate or AutoPay section), card standing instructions, and e-mandates registered with your bank. Recurring card and UPI payments above certain amounts require extra authentication, but small ones can renew without any prompt.
B. Bank and financial fees
- Minimum balance penalties and monthly or quarterly account maintenance fees
- ATM fees after you exceed free monthly transactions
- Annual and renewal fees on credit cards whose rewards you don’t use enough to justify them
- Foreign currency markups on international or overseas-merchant purchases
- Late payment fees, plus interest on revolving balances
- SMS alert charges, debit card annual fees, cheque book charges, and demand draft fees
- Taxes charged on these fees. In India, GST applies to many bank and card charges, so the true cost is higher than the listed fee
Check your bank’s current fee schedule, which is published on its website, since fees change and differ by account type.
C. Insurance and renewals
- Policies that auto-renew at higher premiums without you comparing alternatives
- Duplicate coverage, such as the same phone, travel, or accident cover through your card, your employer, and a separate policy
- Add-ons bundled at purchase that you never reviewed
- Coverage amounts that no longer match your life, for example, too low after a big life change, or too high for an asset you’ve since sold
D. Utilities and telecom
- Phone or internet plans priced for usage you no longer have
- Promotional rates that expired and rolled to the standard price
- Extra connections, TV packages, OTT bundles, or data add-ons that nobody uses
- Multiple SIMs where one is rarely used but still needs recharging to stay active
- Standby power from old devices and appliances left on, which is small but constant
E. Convenience spending
- Delivery fees, platform fees, packaging fees, and surge charges on food and grocery apps
- Daily coffee, snacks, and vending purchases
- Paid parking, tolls, and ride-hailing on routine trips
- Impulse add-ons driven by “free delivery above X” thresholds
- Paid memberships that exist mainly to reduce delivery fees, which only pay off if you order often
F. Lifestyle inflation
Your income rose and your spending rose to match. No single decision was wrong, but your savings rate stayed flat or fell. A useful test: if your income went up in the last two or three years, did your monthly savings go up by a similar percentage? This is the hardest leak to spot because it feels like progress.
G. Debt-related costs
- Buy-now-pay-later and “no-cost EMI” offers. These can still carry processing fees, interest hidden in a reduced discount, or taxes on the interest portion. They also encourage purchases you might not otherwise make
- Interest on credit card balances when you pay only the minimum
- Processing fees, insurance bundled into loans, and prepayment or foreclosure charges
- Multiple small loans, each with its own fees
To see what a loan really costs each month, enter the principal, rate, and tenure into the EMI Calculator. Then compare that EMI with what your budget can actually carry.
H. Irregular costs you didn’t budget for
Annual domain or software renewals, vehicle servicing and insurance, school fees, festivals, gifts, travel, and medical or dental work. These feel like surprises but are predictable. They end up being paid from savings because no monthly budget line covered them.
Related reading on this site:
- How Much Do Braces Cost Without Insurance? (2026 Price Guide): an example of a large, predictable-in-advance medical cost that people often pay from savings
- How to Budget for a European Trip Without Losing Control of Your Finances: useful for planning travel costs, including currency and card fees, before they hit your statement
3. A step-by-step method to find them
Step 1: Gather 90 days of data
Download statements from every account: bank accounts, credit cards, wallets, and payment apps. Three months catches most monthly charges, and six months also catches quarterly ones. If you can, go back 12 months for annual renewals. Include cash spending you can account for.
Tip: Most banks let you export statements as PDF or CSV from net banking. Payment apps usually have a transaction history export or a monthly statement option.
Step 2: Put everything into one list
Use a spreadsheet or paper. Columns: date, merchant, amount, category, and a recurring yes/no flag. Keep it simple, since a complicated system is one you’ll abandon.
Step 3: Sort by merchant, not by date
Grouping by merchant name makes repeats stand out. The same name appearing three months in a row at a similar amount is a recurring expense.
Step 4: Look for these warning signs
- Charges you don’t recognize. Look up the billing name before assuming fraud, since billing names often differ from brand names
- The same amount on the same day each month
- Small near-identical amounts across different merchants
- Annual charges that appear only once in a year of data
- Amounts that rose between months
- Charges from payment gateways or wallets with no clear merchant attached
If a charge still looks wrong after checking, contact your bank promptly, since dispute windows are time-limited.
Step 5: Check your phone and email separately
Check the subscription settings in your phone’s app store and in each payment wallet. Then search your email for receipt, renewal, trial, your subscription, billing, invoice, and auto-renew. This catches charges that look vague in a bank feed.
Step 6: Add up each category
“Subscriptions: $94 a month” motivates more than a list of individual charges. Also add up annual totals for each category so the real size of the leak is visible.
Step 7: Score each item on three questions
- Did I use this in the last 30 days?
- Would I buy it again today at this price?
- Is there a cheaper way to get the same value?
If the first two are “no,” cancel it. If the third is “yes,” switch. Add a fourth question for anything bought for a goal: does this still help me with that goal?
Step 8: Cancel, downgrade, or negotiate
- Cancel what you don’t use, and note the cancellation date and any confirmation email.
- Downgrade tiers: annual vs. monthly, ad-supported vs. premium, family vs. individual.
- Call providers and ask about retention offers or current plans. Long-term customers often pay more than new ones.
- Switch to annual billing only for services you’re sure you’ll keep, since it’s often cheaper.
- Pay credit card balances in full to eliminate interest.
- Ask your bank to switch you to a zero-balance or lower-fee account if you’re paying maintenance fees.
Step 9: Redirect the saved money immediately
If you cancel $60 a month of charges but the money stays in checking, it will probably get spent. Set up an automatic transfer to savings on the day your salary arrives. If you hold debt, you may get a better return by directing the money to your highest-interest balance first.
Step 10: Verify the next statement
Confirm that cancelled charges have actually stopped. Some services keep billing until a second confirmation step or until the current billing period ends.
4. A worked example
Illustrative numbers, not real data:
| Item | Monthly cost |
|---|---|
| 3 unused streaming/app subscriptions | $32 |
| Gym membership (visited twice) | $40 |
| Bank maintenance fee (avoidable) | $8 |
| Cloud storage plan (more than needed) | $10 |
| Delivery and service fees | $45 |
| Phone plan higher than usage requires | $15 |
| Total | $150 |
That’s $1,800 a year. Cutting two-thirds still frees about $100 a month, or $1,200 a year, without touching anything essential.
Reading the result: the biggest line isn’t a subscription; it’s convenience fees. That’s common, since the largest leaks are often spread across habits rather than sitting in one recurring charge. This is why checking both categories matters.
What to do with the freed amount: split it. For instance, half toward an emergency fund until it covers several months of expenses, and half toward a goal such as paying down a loan. To judge whether prepaying a loan makes sense, check its remaining EMI and tenure with the EMI Calculator.
5. Habits that stop the leaks from returning
Run a monthly 15-minute review. Scan your statement once a month instead of doing a big audit once a year. Pick a fixed date, such as the day after your salary arrives.
Use a separate card or account for subscriptions. Recurring charges then appear in one place, and cancelling is easier. Keep only a small balance in it.
Set calendar reminders before renewals and trial expirations. Put the reminder two or three days before the charge, not on the day.
Use a waiting rule for impulse purchases. Wait 24 to 48 hours before buying something unplanned. Many wants fade in that time.
Pay yourself first. Automate savings so what remains is what you spend.
Create a sinking fund for irregular costs. Divide the annual amount by 12 and move it monthly into a separate account. Examples: vehicle insurance, travel, medical or dental costs, school fees, and festival spending. Businesses use the same idea for large purchases; see How Seasonal Businesses Can Plan for Large Equipment Purchases.
Review insurance, phone, and internet annually. Compare current offers rather than accepting automatic renewals.
Don’t treat “no-cost EMI” or “free trial” as free. Check processing fees, price markups, taxes, and cancellation terms. Run the numbers with the EMI Calculator before committing.
Track cash flow, not just spending. Knowing when money arrives and leaves prevents overdraft fees and late-payment charges. The same principle applies at business scale; see 4 Common Cash Flow Mistakes Small Business Owners Make.
6. Mistakes to avoid
- Cutting everything at once. Aggressive cuts rarely last. Remove waste first and keep what you enjoy.
- Ignoring small amounts. Small recurring charges are the entire point of this exercise.
- Cancelling without checking contracts. Some plans have early-termination fees or fixed terms.
- Skipping the follow-up. Verify on your next statement that the charge stopped.
- Assuming annual fees are always bad. A card or membership can be worth its fee if you use the benefits. Calculate the value you actually receive.
- Confusing cheap with valuable. A $5 charge you never use is more wasteful than a $40 one you use daily.
- Forgetting shared accounts. Household members may have subscriptions on your card or shared UPI mandates you haven’t seen.
- Moving the leak rather than closing it. Cancelling one service and signing up for a similar one is not a saving.
- Not testing a decision with numbers. Before taking on any new recurring payment or loan, calculate the total cost over its full term.
Bottom line
Savings rarely fail because of one large mistake. They erode through recurring costs nobody is watching. The fix isn’t extreme frugality; it’s visibility. Once every recurring charge is visible, you can decide on purpose which ones deserve your money. A single focused audit often frees a meaningful amount each month, and the real gain comes from automatically redirecting it into savings.
Want to go further? Browse more articles on the MoneySideOfLife Blog, try the EMI Calculator, learn about the site on the About page, or reach out through Contact.
This is general educational information, not personalized financial advice.