
Money talk is often wrapped in jargon, charts, and confident predictions that leave most people more confused than when they started. This investment guide dismoneyfied takes the opposite approach. It removes the complicated vocabulary and focuses on the habits and decisions that matter most when you are building wealth over time.
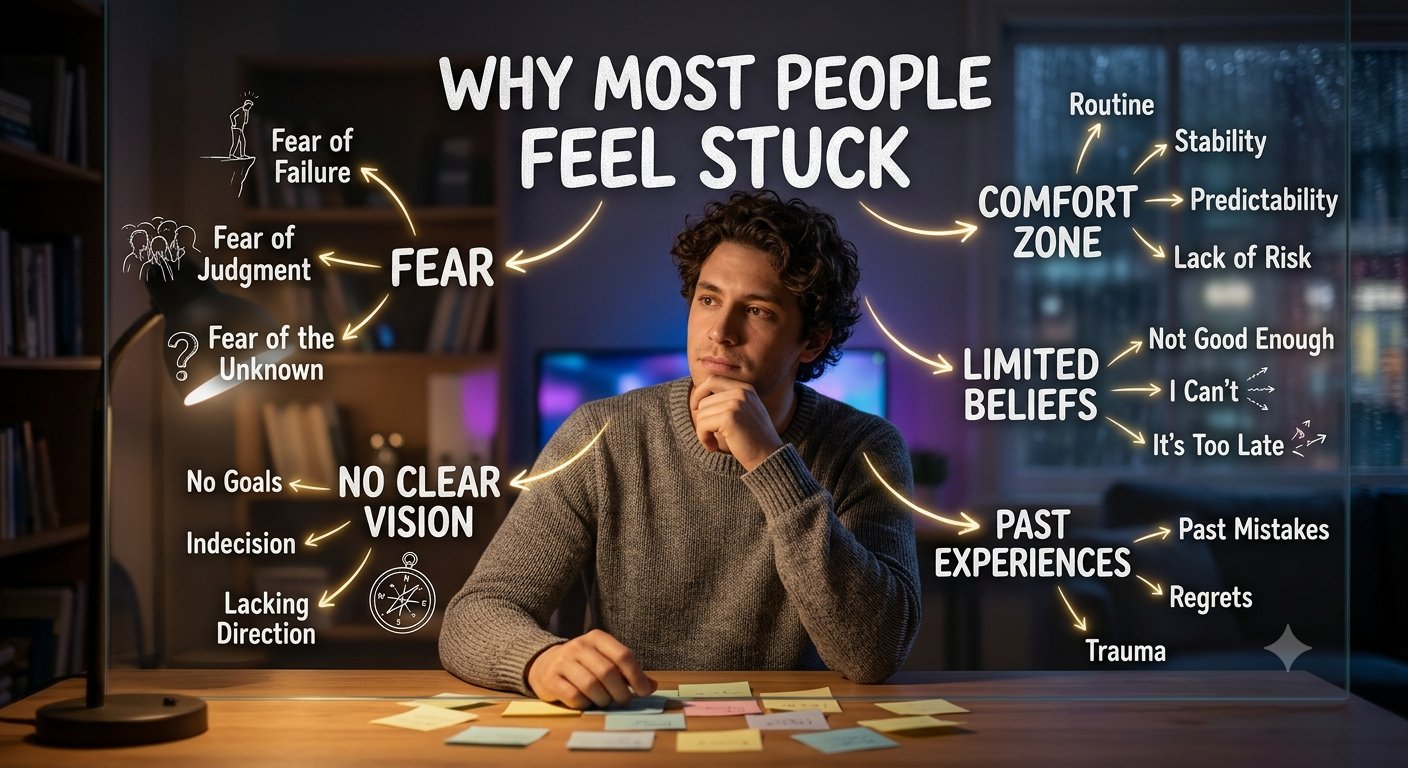
Why Most People Feel Stuck
Many first-time investors delay because they believe they need a large amount of money or deep market knowledge. Neither is true. What you need is a clear purpose, a simple plan, and the patience to follow it. The rest of this article walks through that process step by step.
Step 1: Build Your Safety Net First
Before putting money into any market, make sure you can handle surprises. Set aside enough cash to cover several months of essential expenses, such as rent, food, and bills. If you have loans, include your monthly instalments in that figure. You can check them quickly with the EMI Calculator on MoneySideOfLife. In any investment guide dismoneyfied style of planning, this step comes first because it protects everything that follows.
Step 2: Define What the Money Is For
“Getting rich” is not a goal you can plan around. Specific goals are. Ask yourself:
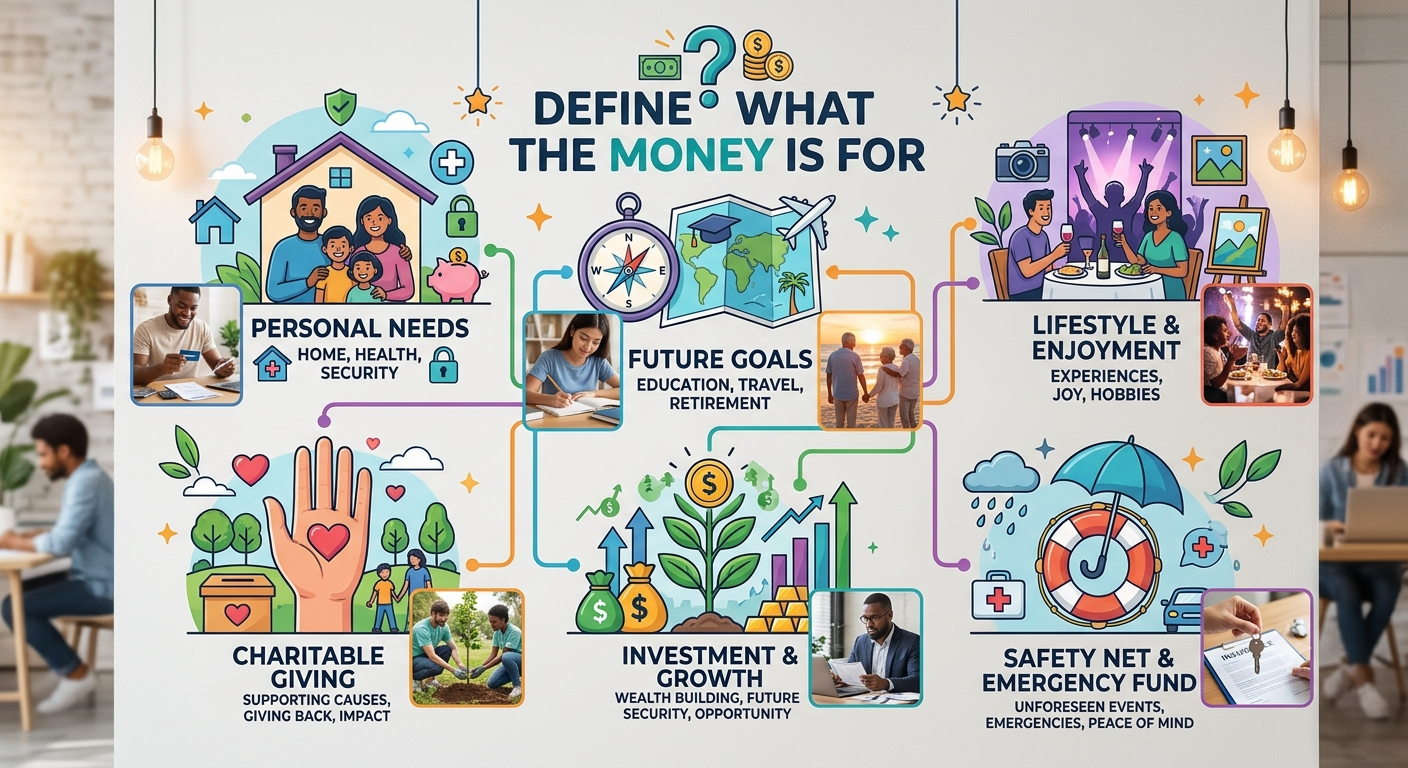
- Am I saving for retirement, a home, education, or a business?
- When will I need this money: in two years, ten years, or thirty?
- How would I feel if my balance dropped by a quarter for a while?
Short-term goals generally call for safer, more stable options. Long-term goals can tolerate more ups and downs because there is time to recover from them.
Step 3: Understand the Main Asset Types
You do not need to master every product. Start by knowing the basics:
- Stocks represent ownership in companies. They offer higher growth potential with higher volatility.
- Bonds are loans to governments or companies that pay interest. They are usually steadier but grow more slowly.
- Funds (index funds, mutual funds, and ETFs) bundle many investments into one, giving you instant diversification.
- Real estate and gold are alternatives some people add for variety, though they come with their own costs and risks.
- Fixed deposits and savings instruments suit money you cannot afford to risk.
- Crypto assets are a newer and far more volatile category. If you are curious, read what “to the moon” means in crypto and the risks behind the hype before putting in any money.
The practical lesson of this investment guide dismoneyfied framework is that a mix of these, matched to your timeline, usually beats chasing a single “hot” option.
Step 4: Diversify, Don’t Gamble
Putting everything into one stock, one sector, or one trend is closer to betting than investing. Spreading money across different asset types and industries reduces the damage if any single piece performs badly. Low-cost index funds are a popular way to do this because they hold hundreds of companies at once and charge small fees.
Step 5: Invest Regularly, Not Perfectly
Trying to time the market is exhausting and rarely works, even for professionals. A calmer method is investing a fixed amount at regular intervals, often called systematic investing. When prices are low, your money buys more units. When prices are high, it buys fewer. Over the years, this smooths out your average cost and removes the pressure of guessing the right day. This is the habit at the center of every investment guide dismoneyfied reader’s plan: steady contributions matter more than perfect entry points.
Step 6: Watch the Costs
Fees look small but compound against you just like returns compound for you. A difference of one percent a year in fund charges can cost a meaningful amount over decades. Compare expense ratios, avoid unnecessary trading, and understand the tax treatment of your investments in your country. This applies to crypto too, where spreads, GST, and TDS can reduce what you actually receive. The breakdown in What Does It Really Cost to Cash Out Crypto? shows how those charges add up.
Common Mistakes to Avoid
Even sensible people repeat the same errors:
- Following the crowd. By the time an investment is trending everywhere, much of the easy gain may be gone.
- Panic selling. Markets fall periodically. Selling after a drop locks in the loss.
- Ignoring inflation. Money left idle slowly loses purchasing power.
- Borrowing to invest. Leverage magnifies losses as well as gains, and loan repayments continue even when your investments fall.
- Trusting guaranteed-return promises. If someone promises high returns with no risk, treat it as a warning sign.
A strong investment guide dismoneyfied approach teaches you to recognize these traps early and stay disciplined when emotions run high.
Review, Then Leave It Alone
Check your portfolio once or twice a year. Rebalance if one part has grown far larger than you intended, and adjust when your life changes, such as a new job, marriage, or children. Beyond that, resist the urge to tinker daily. Constant watching tends to produce constant reacting, and the best investment guide dismoneyfied advice is often simply to wait.
Final Thoughts
Investing does not require genius, secret tips, or a fortune. It requires a safety net, clear goals, diversification, steady contributions, low costs, and patience. If you remember only one idea from this investment guide dismoneyfied overview, let it be that consistency beats cleverness. Start small, stay steady, and keep learning. For more plain-language money guides, browse the MoneySideOfLife blog.
